
July’s housing numbers are in, and the summer sales bump didn’t carry through the way June data suggested it might. The market is still ahead of last year, but the near-term picture just got a bit more cautious.
According to the National Association of Realtors (NAR), existing home sales totaled 400,000 in July, down -5.7% from a revised June figure of 424,000 (revised up from the initially reported 422,000), and up +2.8% year over year compared to July 2025’s 389,000. The seasonally adjusted annualized rate (SAAR) came in at 4.06 million, down -1.7% from a revised June figure of 4.13 million, but still up +0.7% from a year ago.
Inventory pulled back along with sales. NAR reported 1.54 million units of housing inventory in July, or 4.6 months of supply, down -1.9% from June and down -0.6% year over year. That’s the first annual decline in supply we’ve seen in a while, worth watching heading into the fall.
Prices keep climbing. NAR put the national median existing home price at $434,100, up +2.0% year over year, marking the 37th straight month of annual gains.
On the financing side, Fannie Mae now expects 30-year mortgage rates to average 6.5% in 2026 and 6.7% in 2027, up from last month’s 6.3% estimate, while the Mortgage Bankers Association projects 6.7% in both years.
Current Forecasts
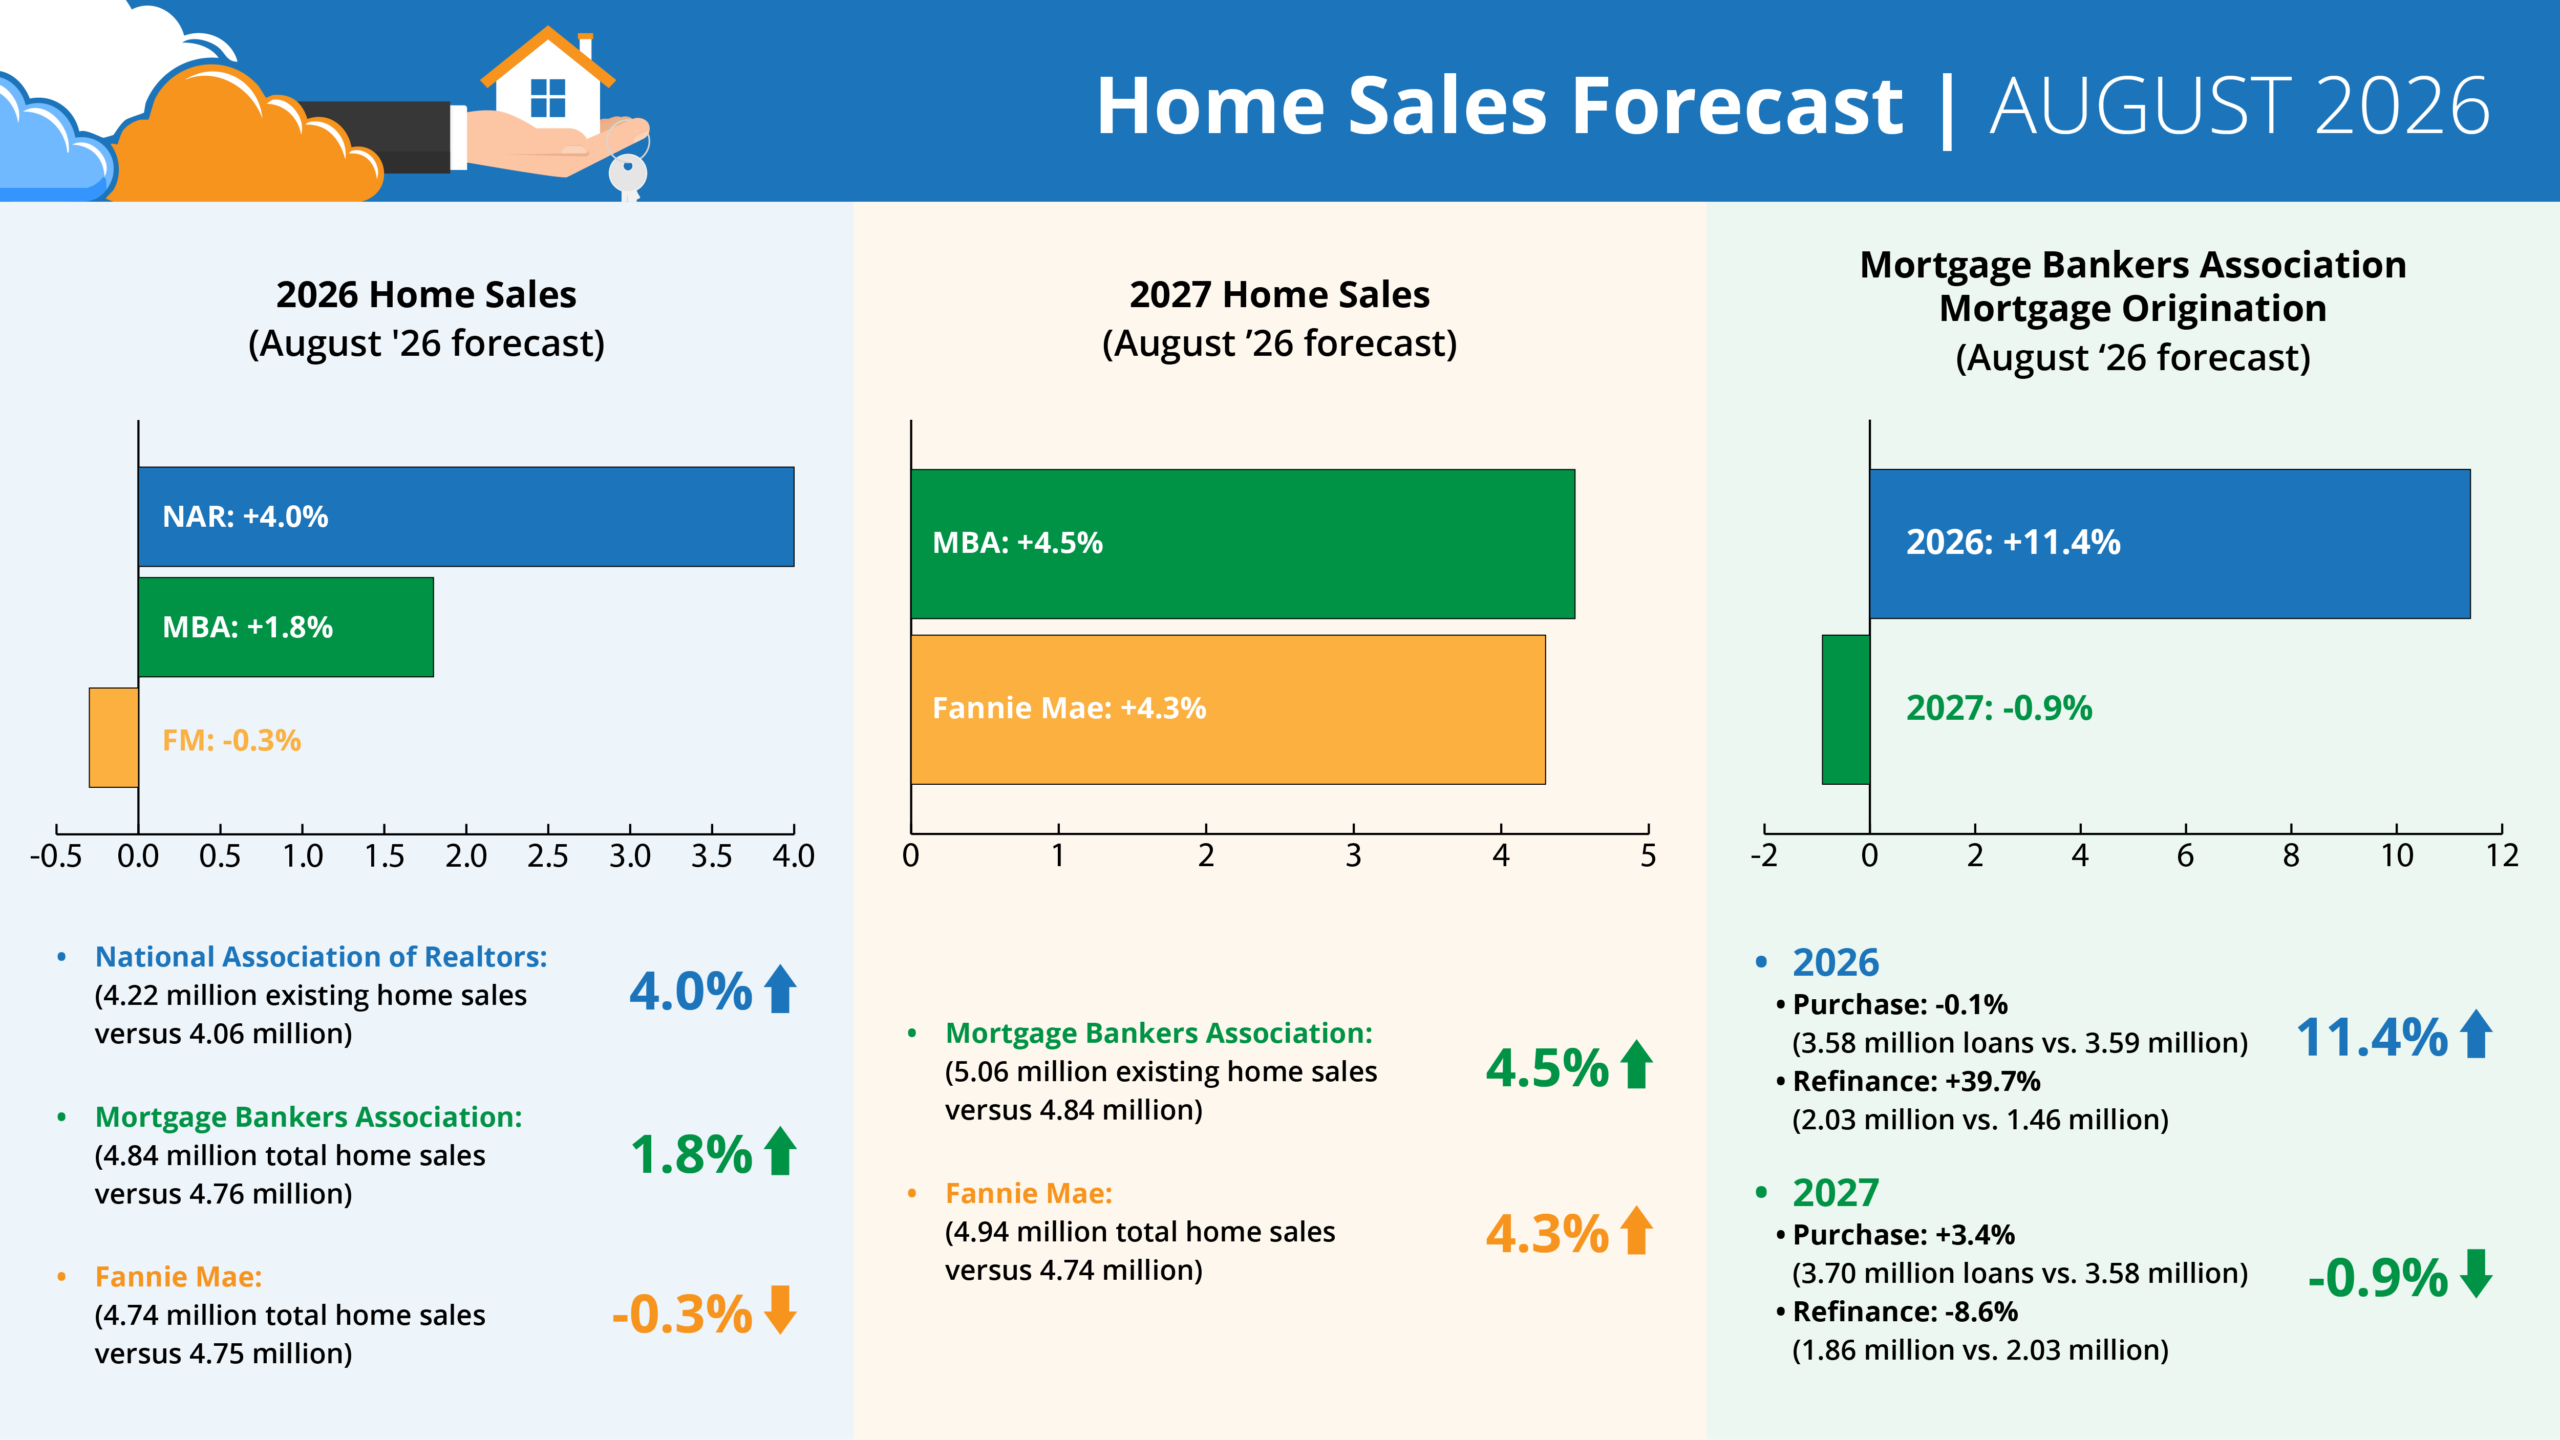
Forecasts for 2026 Home Sales (August ’26 forecast)
- NAR: +4.0% (4.22 million existing home sales vs. 4.06 million), revised April 2026
- MBA: +1.8% (4.84 million total home sales vs. 4.76 million)
- Fannie Mae: -0.3% (4.74 million total home sales vs. 4.75 million)
Forecasts for 2027 Home Sales (August ’26 forecast)
- MBA: +4.5% (5.06 million total home sales vs. 4.84 million)
- Fannie Mae: +4.3% (4.94 million total home sales vs. 4.74 million)
MBA Forecast for Mortgage Originations (August ’26 forecast)
- 2026 Total Mortgage Originations: +11.4% (5.62 million loans vs. 5.04 million)
-
- Purchase: -0.1% (3.58 million loans vs. 3.59 million)
-
- Refi: +39.7% (2.03 million vs. 1.46 million)
- 2027 Total Mortgage Originations: -0.9% (5.56 million loans vs. 5.62 million)
-
- Purchase: +3.4% (3.70 million loans vs. 3.58 million)
-
- Refi: -8.6% (1.86 million vs. 2.03 million)
Bottom line for inspectors
Sales momentum eased in July, and rising rate forecasts suggest the near-term picture may stay a bit softer. Inventory tightened right along with sales, so the market isn’t flooded, it’s just moving more cautiously than it was mid-summer.
With mortgage rates now expected to run higher than last month’s forecast, buyers may take a bit more time to commit. Keep your inspection calendar flexible and your communication proactive so you’re ready whether bookings pick back up or level off.